Showing posts with label ROCKEFELLER. Show all posts

Thursday, February 22, 2007

The Rockefeller Bloodline


The Rockefeller Bloodline
One of the 13 Satanic bloodlines that rule the world is the Rockefeller bloodline. Today, there are around 190 members of this family with the Rockefeller name and of course some others by other last names. This article is to explore further for those who investigate the Illuminati, how the Rockefeller bloodline is involved in the promotion of the occult and Satanism, and how they are involved in the control of the Christian denominations.
This article keys in on just one family, the Rockefellers. To understand the full extent of the Illuminati’s control of religion, including Christendom, would require perhaps several books. The Illuminati itself draws its lifeblood from around 500 very powerful families worldwide. This article will not attempt to explain their networks and the many organizations of the Illuminati. It will not even try to do this for the Rockefellers. In fact, no one knows how many trusts and foundations the Rockefellers have.
They have hidden trusts within secret trusts within secret trusts. It is estimated that they have between 200 and several thousand trusts and foundations. The finances of the Rockefellers are so well covered that Nelson Rockefeller did not pay one cent in income taxes in 1970, yet he was perhaps the richest man in the U.S. The Rockefellers exert enormous influence over religion in this nation in the following ways:
1. They provide a large share of the money that Seminaries in the United States need to operate.2. They provide a large share of the money that universities need to operate. Education influences the religious values of our people.3. They provide large grants to various religious organizations.4. Their influence and control helps determine who will get publicity in the major news magazines, and on television.5. Their influence has contributed to various anti-Christian organizations being set up.6. They directly help control certain religious groups such as Lucis Trust.
The Rockefeller’s influence is both subtle and not so subtle.In the book The Unholy Alliance details are given on how the seminaries, church boards and Christian colleges have been captured. Much of the money for this came from the Rockefellers. One of the principle large Foundations that was instrumental in controlling religious institutions of various kinds was the Sealantic Fund. (They have now shifted to other channels.) This Foundation which was incorporated in 1938 and was headquartered in New York City (50 West 50th St.) gave enormous sums of money to manipulate Protestant concerns. In 1964, according to the Russell Sage Foundation’s book The Foundation Directoy the Sealantic Fund gave away $681, 886 in grants.*
In 1969, the Fund gave $1,889,550 in grants.**
By 1984, the Sealantic Fund was not being used. But a look at another Rockefeller non-profit untaxed Foundation the Rockefeller Brother’s Fund shows a revealing grant pattern. Many people would not be able make any sense out of what seems a random pattern of grants without the broad picture of what the Illuminati is doing today. My book Be Wise As Serpents should have clarified how those various groups who receive grants are related and helpful to the Rockefeller agenda. Although these other Rockefeller Foundations are not specifically geared toward religion such as the Sealantic Fund was, it is clear these other Foundations still impact religion.4 SELECTED GRANTS IN 1984 OF THE ROCKEFELLER BRO. FUND***
Council on Foundations- $41,000
(This money was according to R.B. Fund info ‘Toward work of project which will carry out recommendations from study that points out lack of knowledge about global interdependence and about relationship between international and domestic issues. Emphasis will be placed on information and educational programs to help funders become more familiar with and learn how to analyze opportunities for international grant making.)
Harlem Interfaith Counseling Service-$100,000.
Private Agencies Collaborating Together - $25,000
(“encourages collaboration among private development agencies working in Africa. Asia, and Latin America...”)
Trilateral Commission - $240,000
8 SELECTED GRANTS IN 1984 OF THE ROCKEFELLER FAMILY FUND & ROCKEFELLER FOUNDATION****
ACLU -$15,000,
AMERICAN HISTORICAL ASSOC. -$42,000,
AMER. PHILOSOPHICAL ASSOC. -$57,500,
CATHOLIC UNIVERSITY OF AMERICA -$25,000,
CATHOLIC UNIV. OF CHILE - $224,200,
COUNCIL ON FOREIGN RELATIONS -$165.000,
NAACP- $100,000,
POPULATION COUNCIL - $ 1,235,000,
UNIV. OF NOTRE DAME - $25,000
Catholic institutions have been large recipients of grants from foundations connected to the World Order. The Catholic Church, the Episcopalian Church, and the Unitarian-Universalist Church are all playing big roles in the New World Order for the Satanists. One ex-Satanist has talked about visits that were made with the Pope and Vatican leaders, where the Pope dealt with this person as a member of the Illuminati. In other words the Pope was not in the Illuminati hierarchy, but he carries out transactions with them, and coordinates his actions according to their instructions. We will now go into some depth on the six items above.
1. They provide a large share of the money that Seminaries in the United States need to operate.
The Union Theological Seminary has operated from Rockefeller funds.*****
UTS hasn’t been the only Protestant Seminary receiving Rockefeller funds, but it may be the best example of a seminary controlled by the Rockefellers.

The Sealantic Fund stated under its purpose and activities, “Current interests are primarily Protestant theological education...... ******
The President of the Sealantic Fund when it operated was David Rockefeller, and Laurance (not Lawrence) S. Rockefeller was Vice-President. Steven C. Rockefeller was one of the trustees.
2. They provide a large share of the money that universities need to operate. Education influences the religious values of our people.In 1952, Congressman Eugene E. Cox headed up a committee that for the first time tried to uncover the Rockefeller’s (and other’s) foundations’ activities. For some reason, Cox encountered stiff opposition everywhere against his committee’s investigation, and the Congressman for some reason got sick and died. One member of the committee, Congressman Carroll Reese, and his Counsel Rene Wormser attempted to continue the investigation. Rockefeller’s henchmen and newspapers did their best to destroy Congressman Reese.
The Reese investigation was given only the barest minimum of time and little resources for their investigation. However, they were still able to uncover that beginning in the 1930s vast sums of money were spent in Education by the Rockefeller and Carnegie foundations. This money went to promote John Dewey, Marxism, a One-World-Government agenda, and Socialism. The foundations (principally the Rockefeller and Carnegie) stimulated two-thirds of the total endowment funding of all institutions of higher learning in America during the first third of this 20th century.*******
The NEA (National Education Association was largely financed by the Rockefeller/Carnegie foundations. A 1934 NEA report advised, “A dying laissez-faire must be completely destroyed and all of us, including the ‘owners’, must be subjected to a large degree of social control.” Reece Committee Counsel Rene Wormser wrote of the investigation, “...leads one to the conclusion that there was, indeed, something in the nature of an actual conspiracy among certain leading educators in the United States to bring about socialism through the use of our school systems...” They discovered that the Rockefeller foundation was the primary culprit behind the teaching of socialism in America’s schools and universities and also behind the NEA’s policies. Rene Wormser, Counsel for the Reece Committee reported, “A very powerful complex of foundations and allied organizations has developed over the years to exercise a high degree of control over education. Part of this complex, and ultimately responsible for it, are the Rockefeller and Carnegie groups of foundations.”
This was the situation in the 1950s when the Reece Committee briefly investigated. The Rockefeller-Carnegie groups have continued basically unopposed for the next 40 years in controlling education. One of the educational book producers is Grolier, Inc. Avery Rockefeller, Jr. sits on Grolier, Inc. board meetings. Another interesting board member is Theodore WaIler who is the director of Grolier, Inc. He was a member of the International Book Committee of UNESCO. The Rockefellers maintain great influence in the United Nations.3. They provide large grants to various religious organizations.On Jan. 31, 1945, John D. Rockefeller addressed the Protestant Council of the City of N.Y. and told them that the answer to the problems Christianity was that Christianity needed to become “the Church of the Living God.” Many listening that day, may not have realized that he and other top Illuminati consider themselves gods, and that the solution John D. was cryptically giving was for Christianity to serve him a living god. (Rockefeller, John D. The Christian Church- What of its Future? NY:Protestant Council, 1945, & 1917.)4. Their influence and control helps determine who will get publicity in the major news magazines.The Rockefeller family has enormous controls over various magazines and newspapers. Let us examine how the power of the press can be used in religion. One of the magazines that the Rockefellers have some control over is Time magazine. Time’s board chairman, Andrew Heiskell was associated with David Rockefeller. Another Illuminatus of the 6th level1 Henry J. Fisher, ran McCall’s Magazine from 1917 to 1956. The establishment’s media boosted Anton LaVey’s Church of Satan into prominence. The Jan. 31, 1967 New York Daily News ran a story about Anton LaVey performing the first Satanic wedding ceremony in America. The March 1970 issue of McCall’s ran a nice story about the Church of Satan. Not only is LaVey’s Church of Satan a publicity stunt to make Satanism more popular and to deflect criticism of real covert Satanism, the McCall issue makes Anton LaVey’s church sound even better in the article than it is.
(For those brainwashed folks who think that this free advertising for Anton LaVey was just for the sake of finding a good story for the Daily News and McCall, I can show you dozens of better juicier stories that never have seen the light of day--because they are contrary to what the Illuminati want people to hear. I won’t argue that a story on Satanism may be interesting, I am pointing out that many other interesting stories don’t get printed. Stories are selected by an editor, they don’t just happen.)

Finally on June 19, 1972 Time Magazine provided more coverage for LaVey with an article “The Occult: A Substitute Faith.” Believe me, the sincere devout Christian groups haven’t ever received such nice free publicity. I’m not referring to men like 33° Mason Billy Graham, who works for the New World Order and Knights Templar Mason Charles T. Russell, founder of the Watchtower Society who both received great press coverage. Another minor example, and I am pointing out minor examples because they occur many times during the course of year, is Van Daniken’s UFO books. Lew Wasserman, head of MCA, which owns G.P. Putnam’s Sons, is a member of the Rockefeller University Council. G.P. Putnam’s Sons published Van Daniken’s anti-Christian UFO religious theories. Cadence Industries own Marvel Comics. The men on the board of Cadence sit under David Rockefeller in places like the CFR. Is it any wonder Marvel Comics promotes the occult and heroes like ‘The Son of Satan”? Where does the buck stop? You say that the Rockefellers don’t control subordinates.
Bear in mind, that many of the Rockefellers call themselves Baptists. If they are really Christians don’t you think they could use their influence to stop such terrible things? The point is that the rottenness starts at the top. The rest of the pyramid has a hard time turning out O.K. when the top of the pyramid is dedicated to Satan. Rockefeller and Hearst worked together in their news monopolies. It was Hearst who promoted both books on Satanism and Billy Graham. (If you learn what I know--the two are not contradictory.) Hearst made Billy Graham who he is today by financially backing him and publicizing him. Rockefeller was supportive of Billy Graham’s New York Crusade, and the Manhattan-Chase Bank helped Billy Graham out.
5. Their influence has contributed to various anti-Christian organizations being set up.Maurice Strong is a good friend of the Rockefellers. He has been promoting Mother Gaia worship. David Rockefeller works with Maurice Strong and his New Age ideas. Reverend Moon from Korea has been very much loved by the Rockefellers. Moon calls himself Christ and is setting up a religion promoting internationalism. His religion is also a good testing ground for brainwashing/recruiting techniques that are being perfected by the NWO. The Rockefellers have been helping Moon, who also has his primary mansion in NY. Also of interest is that the prominent political figures that have endorsed Moon are those with ties to the NWO, and include Ted Kennedy, Mason Mark C. Hatfield, Mason Jesse Helms, & Illuminatus William F. Buckley, Jr. (See pg. 32-33 of The Puppet Master by J. Isamu Yamamoto.) A lesser known group is the Spiritual Frontiers Fellowship (SFF) in Independence, MO. Their address was Exec. Plaza, 10715 Winner Rd, 64052. They were founded in 1956. Just like Reverend Moon they claim to be Christians, but teach and practice other things. They teach and practice the occult. Two prominent men in SFF are Marcus
Bach and Gardner Murphy. They both have interesting backgrounds. Marcus Bach shows the touch of the Rockefellers. Marcus Bach, born in 1906, is director of special projects for SFF. The Rockefeller Foundation granted him a fellowship in “research and creative writing” from 1934-36. Gardner Murphy was the consultant in 1950 for UNESCO in New Delhi to the Hindus of the Indian Ministry of Education. From ‘52-’68 he was director of research at the Menninger Foundation, Topeka, KS. (Yes, psychology is led mainly by occultists!) Menninger himself is a member of several environmental groups for the elite, an Honorary trustee of the Aspen Institute, a Freemason, member of ACLU, and a close associate of W. Clement Stone. W. Clement Stone in turn is also a Mason, a member of the occult American Society for Psychical Research, and the financial backer of the Menninger Foundation.
The Federal Council of Churches was financed to a large extent by Rockefeller money. In my Be Wise As Serpents book I detail how the FCC was designed to destroy Christianity, how they carefully plotted to make the creation of the FCC look like a grass roots movement, when it was actually the creation of the elite (Illuminati). I further detail how the men who ran it were high ranking Masons, Socialists, and One-Worlders. Also shown is how they carefully manipulated the real gospel for their own devious ends.
6. They directly help control certain religious groups such as Lucis Trust.David Rockefeller is part of Lucis Trust’s management. Lucis Trust puts out the book Externalization of the Hierarchy by Alice Bailey which spells out The Plan for the Satanists and New Agers on how the spiritual Hierarchy (actually the demonic hierarchy) is to externalize their rule of the planet. The book gives quite a few of the details of the plan, and is used as a textbook for New Agers at the Arcane Schools in NY, London, and Europe on how the New Age/One World Religion/One-World-Government will be brought in. If anyone doubts the Rockefeller’s commitment to Satan, read page 107 of Externalization of the Hierarchy. On page 107 Alice Bailey, President of the Theosophical Society and part of Lucis (formerly Lucifer) Trust, tells us who will rule when the New Age (New World Order) takes over.
On the Earthly level--Humanity so to speak, the Ruler is given on page 107 as Lucifer. On the Spiritual level--called “Shamballa - the Holy City” the coming ruler is given as “the Lord of the World” which we Christians know as Satan. Lucis Trust knows it is Satan too, but for public consumption they say that the “ruler of the world” is Sanat (a scrambling of Satan) Kumara. They also predict there will be a Christ Consciousness and the Christ (actually the Anti-Christ) The book Externalization of the Hierarchy teaches repeatedly (see pages 511-512, 514) that the 3 vehicles to bring in the New Age will be the Masonic Lodges, (obviously not everyone attends Lodges), next the Churches (this is clearly revealing to us that men like the Rockefellers are using the churches for the Luciferian plan of Lucis Trust), and finally Education (Well, of course education. Not everyone attends churches.
They need a safety net to catch everyone in their brainwashing to make us all want to be happy slaves under the Light-bearer.) The home life of the Rockefellers is decidedly different than for most people. They have over 100 homes to stay at. The Rockefellers own vast tracts of good land in various countries in South America, and have nice homes in Brazil, Ecuador, and their Monte Sacro Ranch, Venezuela. They have two mansions in Washington, D.C. (at least), numerous ranches around the United States, resorts in Hawaii, Puerto Rico, and the Caribbean, a 32- room 5th Ave duplex in N.Y., not to mention their place at Seal Harbor, Maine, and the large estate at Pocantico Hills, NY. It is estimated that they have 2,500 house servants.
Over the years, they have built up the reputation of being miserly with their help, and to each other. (I couldn’t begin to know all about the Rockefellers, but I can give a sampling of some of the many items that surround the real lives of America’s top Illuminati family.) Winthrop, who is homosexual,, enjoyed living in Arkansas with his black male friend. He reportedly had the world’s largest porn collection. Winifred Rockefeller Emeny, Nelson’s cousin, murdered her two children and committed suicide.
Michael Rockefeller died when he tried to bribe New Guinea tribesmen with large sums of money to go head hunt and make shrunken heads for him. The natives had given up head hunting and Michael couldn’t sucessfully bribe them. Finally getting tired of Michael, the natives decided to head hunt Michael himself!
Many of the Rockefeller family have had troubled lives, filled with all kinds of fears and occult activities. It is known that the Rockefellers have frequently built many hidden tunnels and hidden rooms onto their buildings. They have developed their occult and worldly powers to the point they consider themselves gods. Their powerful often suffer violent ritual death as most high level Satanists traditionally go through. One who died in Arizona is known to have been cremated.

John D. Rockefeller Sr.

ENDNOTES
* Walton, Ann D. and Marianna O. Lewis, Editors. The Foundation Directory Ed. 2. NY: Published by Russell Sage Foundation, 1964, p.584.
** Lewis, Marianna 0. and Patricia Bowers, Editors. The Foundation Directory Ed. 4. NY: Columbia University Press, 1971, p.342.
*** Garonzik, Elan, ed. compiled by The Foundation Center. The Foundation Grants Index 13 Edition. NY: The Foundation Center, 1984, pp. 369-372.
**** Ibid., pp. 372-373.
***** Allen1 Gary. The Rockefeller File. Boring, OR: CPA Publishers, (reprint of 1976 edition), p. 47.
****** Walton, op. cit.
******* Allen, op. cit., p. 45
PARTIAL BIBLIOGRAPHYBOOKS:
Allen, Gary. The Rockefeller File. Boring, OR: CPA Book Publishers, 1991. (reprint of 1976 ed.)
Bailey, Alice. The Externalisation of the Hierarchy. NY (866 United Nations Plaza!): Lucis Publishing Co., 1982.
Foundation Directories from 1964, 1971, 1984.
Josephson, Emanuel M. The Truth About Rockefeller ‘Public Enemy No 1” Studies in CriminalPsychopathy. NY: Chedney Press, 1964.
Springmeier, Fritz. Be Wise As Serpents. Portland, OR : Fritz Springmeier, 1991.
OTHER:
Interviews--with ex-Illuminati Manuscript--from ex-high ranking Mason who strangely died (it was called a suicide) soon after completing his expose of the New World Order’s elite.
WHY AM I COVERING THE TOP 13 ILLUMINATI BLOODLINES?
I have often been asked who are the Illuminati? Who are the people at the top of the conspiracy? Who are the generational satanic families? The illuminati consists of 13 magical and powerful bloodlines. There are also some other powerful bloodlines that are worth naming but if they are in the Illuminati they have blood ties to one of the 13 powerful lineages. About half of the Illuminati people I know have had their parentage hidden from them. Many of the those who still know who their real parents are, still do not know what bloodline they belong to until the Illuminati chooses to reveal it to them. Most of the Illuminati have MPD. When high level Satanists do not have MPD they very often emotionally break under the stress of the horrible blood rituals that are required. Recently, a non-MPD Satanist in Chicago emotionally broke and gave his life to Christ. (I have videos available of an interview of this man exposing Satanism.) One of the important lineages has remained secret until 3 investigators named Lincoln, Leigh, and Bageant were spoon-fed leads and secrets.
They put this into a book called "Holy Blood, Holy Grail." I recommend the book and the two books which are its sequels, because they show how just one part of the 13 lineages has kept itself secret and has taken immense power of all forms to themselves. In Southern Belgium there is a castle. (If any one is travelling there and wants to find the castle, I will show them on the map, and describe it.) This is the Mothers of Darkness castle. In that castle, is a cathedral and in that cathedral’s basement a little baby Is sacrificed daily and Is coming to power. The pages are written almost round the clock. (This castle is also described in my Be Wise as Serpents book.) The history in that handwritten book would reveal the real facts behind the propaganda that the world’s major news medias give the gullible public. The history as that book reveals it would tell people about how Abraham Lincoln was a descendent of the Rothschilds.
Abraham Lincoln was the secret head of the Rosicrucians, a member of their 3 headed top council. (I have seen the paper trail proof to these things about Lincoln to my satisfaction that these things about Uncoin are true.) Adolf Hitler was also a secret member of the Rothschild lineage. Hitler carried out blood sacrifices to open his mind up to high level demonic spiritual control. Rockefeller sold Hitler oil during W.W. II via Spain to keep W.W. II going longer. The history in that book mentions people that the “history books” given the public don’t-- like Michael Augustus Martinelli Von Braun Rheinhold, the most powerful Satanist in the world a few years ago. Michael Augustus Martinelli Von Braun Rheinhold had 66 Satanic Brides. And that Satanic book in the Mothers of Darkness castle also mentions the Rockefeller bloodline. Only insiders are supposed to know the real history of what has taken place in human history. The real decisions and the real movers and shakers have been hidden from the public’s eyes.
What the public is given is a stage show where illuminati puppets parade around and make big speeches according to their script. Each of the 13 families has their own set of Mothers of Darkness. Each of the 13 families has their own secret Satanic leadership Kings, Queens, Princesses and Princes of Darkness. For instance, the Rockefeller family has people who are selected as Kings and Princes within their own bloodline in secret rituals. The Kings and Princes, Queens and Princesses are strictly bloodline. They secretly rule over an area of the world for their own bloodline. This is independent of the illuminati's hierarchy which was diagrammed in the Jan 1993 newsletter. (my Newsletter from a Christian Ministry.) In the January, 1993 issue the Covens, Sisters of Light, Mothers of Darkness, and the Grande Mothers were diagrammed.
The illuminati pulls its various bloodlines together under several councils. The Grande Druid Council or your Council of 13 is your principle council for the Brotherhood of Death. Above the Council of 13 is a higher Council of 9, and an inner group of 3 is believed to head that Council of Nine. How do we know about these things? The power of God has reached into the very heart of Satan’s empire and pulled out some of the most powerful Satanists and drawn them to Christ. There are several Satanists that were at the top which have managed to find Christ. in addition, some of the next echelon of the hierarchy, such as some of the Mothers of Darkness are also finding Christ. if someone wants to understand how and why decisions are made in world affairs and by who-- then you need to study the illuminati. The real answers do not rest with the proceedings of the Congress of the United States or with the publicly known leaders of the Communist countries. An example of what I am talking, there is a book entitled "Who Financed Hitler" by James Pool and Suzanne Pool. I am always glad to see that some people are wiling to look behind the scenes. Believe me, there were people that Hitler listened to. They were the people he went to ritual with, and who put him into power.
A CONTINUATION OF THE SERIES OF ARTICLES ON
THE TOP 13 ILLUMINATI BLOODLINES.
THE ROCKEFELLER FAMILY
PREFACEThe first article about the House of Rockefeller in this newsletter occurred in the Mid-Dec 1992 Vol. No. 13 Issue pp. 3-8. The primary focus of that article was to show how the family controlled large segments of the Protestant groups in the United States. A secondary focus of that article was to show the Satanic occult side of the family. An attempt will be made in this article not to rehash information given out in that earlier article. The Rockefeller family has been so busy and there Is a large amount of information that can be provided about them. Therefore my goal with this article Li to provide introductory information to the readership, and to qualify that what is written In this article Is but the basics of what should be written about the illuminati activities of this family. Much of my own material on the Rockefeller family was lost this year and I don’t have the time to go back and research it again. Much of it involved the secret wheeling and dealing that went on behind the scenes to bring the Rockefellers into wealth and power. Some of the details also involved their manipulations to control about everything that the Rockefellers can find to control. Some of the research was on the occult activities of the House of Rockefeller.THE FIRST NOTORIOUS ROCKEFELLER.The first notorious Rockefeller that researchers who are not working for the Rockefellers refer to is William Avery Rockefeller (1810 -1906?). William Avery Rockefeller was totally corrupt and lacked any type of morals. He was involved in the occult and practiced magic. He married a number of women around the country in bigamous relationships. He also had a number of mistresses, and a large number of sexual partners. He was charged with raping a women and escaped the state of New York to prevent being sent to Jail for it. He stole, lied, and abused his way through life. He wore the best of clothes, and he never lacked for money, including gold coins. Besides loving women, he loved gambling. And where did his money to gamble with come from?
He made much of his money dishonestly. His life Is a carbon copy of other men who are known by this author to have been in the Illuminati. (The reader also needs to bear in mind that the Illuminati carries out a large number of secret occult marriages, which only insiders learn about.) One of his wives was Eliza Davidson (181349). She was an extremely cruel woman. Historians who have been bought off by the elite like to picture Eliza Davidson as a very pious woman. Although she had a religious front, there are a number of things in her life that show that she was not the paragon of virtue that the paid-for historians have made her out to be. When she married William Avery Rockefeller she moved in with him and his mistress.THE FIRST NOTABLY RICH ROCKEFELLER.William Avery Rockefeller had many bastard children, and it can be imagined many children born for ritual or for the cult. His wife Eliza had six children for him and of those John Davison Rockefeller is the infamous one who brought the family into limelight. John D. Rockefeller in his lifetime became one of the most powerful men in the world. One of the most best kept secrets were his secret dealings with the other Illuminati families. The Payseurs and other Illuminati families are all intimately involved in the rise to power of the Rockefellers. The other factors involved in John D. Rockefeller’s rise to power is his utter ruthlessness. He was willing to do anything for power. John o. Rockefeller established the family in their principal estate at Pocantico Hills in New York. I have lost the exact figure, but over 100 Rockefeller families live at the private land of Pocantico Hills.A BRIEF SURVEY OF THE ROCKEFELLER’S INFLUENCEThe Rockefellers have divested much of their holdings into places which they control, but nominally they are not owners of. The Rockefellers financial power Is far greater than the balance sheets would indicate. The Rockefellers can give donations from an organization which they control to another that they control, and not lose any control over the money. The donations look Impressive, but the Rockefeller bloodline hasn’t lost. Have you ever noticed that Rockefeller’s Standard Oil uses the satanic pentagram in a circle as their logo? Just three of countless Rockefeller companies are Texas Instruments and General Electric, and Eastman Kodak. The Rockefellers also control Boeing. This author (Fritz Sprlngmeier) has repeatedly been given information from numerous sources about the occult activities that are being perpetrated at the Boeing plants in the Seattle area. Monarch programming has even taken place at a Boeing Plant. All these things fit together when one gets the bigger picture and the inside scoop. The Rockefellers also control Delta. Has anyone realized that the Delta symbol is a very widely used satanic symbol? Is It any wonder so many Illuminati and CIA, and world financiers, and people like Chuck Coison (see the exposes on Chuck Colson in 93’s newsletters) use Delta to fly on.
My notes are lost, hut suffice It to say the Rockefellers own land all over South America. The Rockefellers own land most anywhere anyone would want to visit in the US. from Hawaii to Texas to Florida and Seal Harbor, Maine. Notice how often Bush would go to Maine when he was President?
The Rockefellers have played a role in Lucis Trust and the United Nations. Interestingly, you will notice that Prince Charles is the spokesperson for Lucis Trust and also works with the United Nations in various ways. Prince Charles Is from another satanic bloodline. Readers need to study my Be Wise As Serpents book to see how Lucis Trust fits into things. The Rockefellers were involved in the creation of the FBI, so that the FBI has always been an arm of power for the Illuminati. That is why there are official FBI programs in action today to kIdnap children and provide them for sacrifice. Yes, American people, the wolf was set in charge of guarding the chicken coop. The organization that is working as part of the FBI is the Finders. (The stink was so bad that US. News & World Report did a story to soften the impact of the scandal. See the article on a following page.)
Ex-Satanists who worked with the FBI to receive the children the FBI kidnapped and sold to them for sacrifice have been trying to get the word out publicly about the FBI’s corruption. When the Illuminati was beginning to get exposed in the Franklin Saving & Loan case in Lincoln, NE the FBI was part of the dirty actors and was part of the cover up. The Rockefellers have had control over the FBI since they helped get it started. When Congress wanted to investigate the CIA for wrongdoing the appointed a Commission headed by Rockefeller to investigate the CIA’s wrongdoings! Yes, the Rockefeller Commission did a big study and slapped the hands of the CIA for a few misdeeds. Their report is still cited as the big investigation of the CIA. Some investigation! Since the Rockefeller family work hand in hand with the CIA to create Monarch slaves, of course that part of the CIA’s misdeeds got overlooked!
A recent convert from Satanism, Michael McArthur, has given validated inside information about the FBI and the CIA programs which kidnap children in order to supply Satanic rituals with sacrificial material. The names of the agents who spend their official government time kidnapping children for Satanism that Michael knows about are as follows:Chucky “Mike,” “Peters”-FBI hit man in Div, 5 of FBI, involved with inslaw case Nichol Harrah--FBI agent who abducts children for sacrifice
Unda Krieg Satanist working for FBI
Ken Lanning FBI agent who abducts children for sacrifice
Nick O’Hara FBI hit man, satanist, has covered FBI child kidnappings by murder Kape Richardson CIA agent who abducts children for sacrifice
Rather, than risk election, a brilliant coup d’etat which Is exposed in Be Wise As Serpents. was carried out to put Nelson A. Rockefeller into the Vice-Presidency.
The Rockefellers control both education and religion in this country by their foundations.
The Rockefellers have played key roles in the CFR. Rockefeller wrote the book the Future of Federalism which supports the union of nations into a world government. For many years the Rockefellers have been pouring billions of dollars into projects and international groups which are working to bring in a public One-World government. (The world already has a secret One-World-Government.) The Rockefellers take part in decisions that effect Russia, China and other parts of Asla and with good reason, the House of Rockefeller has holdup and assets in these countries too.The investigator of the Rockefellers will find that they have secretly had their hand in the politics of the United States during the 20th century. The decisions and directions this nation has taken, are the result of countless orders which the Rockefellers have given to their underlings.ALONG WITH THIS BRIEF LOOK AT THE ROCKEFELLERS, I HAVE INCLUDED(not included here because not processed in plain text)
A - A BIBLIOGRAPHY BOOKS FOR FURTHER STUDY, B - SOME PAGES SHOWING THE POCANTICO ESTATES, C - SOME PAGES SHOWING PUBLIC MARRIAGES OF THE ELITE.
BIBLIOGRAPHY & SOURCESBooks
Allen, Gary. Rockefeller. Campaining For The New Worid Order. Boring, OR CPA.
Collier, Peter & David Horowitz. The Rockefellers An American Dynasty. New York Holt, Rinehart and Winston, 1976.
Hoffman, William. David, Report On A Rockefeller. New York: Ly1e Stuart, Inc., 1971.
Josephson, Emanuel M. The Truth About Rockefeller “Public Enemy No. 1” Studies in Criminal Psychopathy New York: Chedney Press, 1964.
Mullins, Eustace. The World Order. Boring. OR: CPA.
other interview with an ex-Rockefeller Monarch slave
interviews with ex-Illuminati and others who know things about the Rockefellers

Monday, February 19, 2007

VIDEO:INCOME TAX FRAUD/I.R.S./AARON RUSSO


Historic Interview with Aaron Russo, Fighting Cancer and the New World Order


The Money Masters

"The powers of financial capitalism had a far-reaching plan, nothing less than to create a world system of financial control in private hands able to dominate the political system of each country and the economy of the world as a whole...Their secret is that they have annexed from governments, monarchies, and republics the power to create the world's money THE MONEY MASTERS is a 3 1/2 hour non-fiction, historical documentary that traces the origins of the political power structure that rules our nation and the world today. The modern political power structure has its roots in the hidden manipulation and accumulation of gold and other forms of money. The development of fractional reserve banking practices in the 17th century brought to a cunning sophistication the secret techniques initially used by goldsmiths fraudulently to accumulate wealth. With the formation of the privately-owned Bank of England in 1694, the yoke of economic slavery to a privately-owned "central" bank was first forced upon the backs of an entire nation, not removed but only made heavier with the passing of the three centuries to our day. Nation after nation, including America, has fallen prey to this cabal of international central bankers.


The Fiat Money System - Dr. Bill Veith in studio w/ Alex Jones


You think the United States Government owns the Federal Reserve? Think again, the Rothschild family, the Bank of England, and the London banking houses control the US Federal Reserve Banks through their stockholdings of bank stock and their subsidiary firms in New York. (click for more) To make matters more clear, the Rothchild family is deeply entrenched in freemasonry and the masonic dark arts. (link for info on that)


Rockefeller Admitted Elite Goal Of Microchipped Population Hollywood director Russo goes in-depth for first time on the astounding admissions of Nick Rockefeller, including his prediction of 9/11 and the war on terror hoax, the Rockefeller's creation of women's lib, and the elite's ultimate plan for world population reduction and a microchipped society


Hollywood director and documentary film maker Aaron Russo has gone in-depth on the astounding admissions of Nick Rockefeller, who personally told him that the elite's ultimate goal was to create a microchipped population and that the war on terror was a hoax, Rockefeller having predicted an "event" that would trigger the invasions of Iraq and Afghanistan eleven months before 9/11.
Rockefeller also told Russo that his family's foundation had created and bankrolled the women's liberation movement in order to destroy the family and that population reduction was a fundamental aim of the global elite.
Russo is perhaps best known for directing Trading Places starring Eddie Murphy but was more recently in the spotlight for his exposé of the criminal run for profit federal reserve system, the documentary America From Freedom to Fascism .
Currently undergoing more treatment in his fight against cancer, Russo made time for a sit down interview with radio host and fellow documentary film maker Alex Jones in which he dropped bombshell after bombshell on what Rockefeller had told him about the direction the world was being steered towards by the global elite.
You can watch a fourteen minute segment of the interview below.
After his popular video Mad As Hell was released and he began his campaign to become Governor of Nevada, Russo was noticed by Rockefeller and introduced to him by a female attorney. Seeing Russo's passion and ability to affect change, Rockefeller set about on a subtle mission to recruit Russo into the elite.
During one conversation, Rockefeller asked Russo if he was interested in joining the Council on Foreign Relations (CFR) but Russo rejected the invitation, saying he had no interest in "enslaving the people" to which Rockefeller coldly questioned why he cared about the "serfs."
"I used to say to him what's the point of all this," states Russo, "you have all the money in the world you need, you have all the power you need, what's the point, what's the end goal?" to which Rockefeller replied (paraphrasing), "The end goal is to get everybody chipped, to control the whole society, to have the bankers and the elite people control the world."
Rockefeller even assured Russo that if he joined the elite his chip would be specially marked so as to avoid undue inspection by the authorities.Russo states that Rockefeller told him, "Eleven months before 9/11 happened there was going to be an event and out of that event we were going to invade Afghanistan to run pipelines through the Caspian sea, we were going to invade Iraq to take over the oil fields and establish a base in the Middle East, and we'd go after Chavez in Venezuela."
Rockefeller also told Russo that he would see soldiers looking in caves in Afghanistan and Pakistan for Osama bin Laden and that there would be an "Endless war on terror where there's no real enemy and the whole thing is a giant hoax," so that "the government could take over the American people," according to Russo, who said that Rockefeller was cynically laughing and joking as he made the astounding prediction.
In a later conversation, Rockefeller asked Russo what he thought women's liberation was about. Russo's response that he thought it was about the right to work and receive equal pay as men, just as they had won the right to vote, caused Rockefeller to laughingly retort, "You're an idiot! Let me tell you what that was about, we the Rockefellers funded that, we funded women's lib, we're the ones who got all of the newspapers and television - the Rockefeller Foundation."


Rockefeller told Russo of two primary reasons why the elite bankrolled women's lib: One before women's lib the bankers couldn't tax half the population and two because it allowed them to get children in school at an earlier age, enabling them to be indoctrinated into accepting the state as the primary family, breaking up the traditional family model.
This revelation dovetails previous admissions on behalf of feminist pioneer Gloria Steinem (pictured) that the CIA bankrolled Ms. Magazine as part of the same agenda of breaking up traditional family models.
Rockefeller was often keen to stress his idea that "the people have to be ruled" by an elite and that one of the tools of such power was population reduction, that there were "too many people in the world," and world population numbers should be reduced by at least half.
One issue which has spiraled out of control of the elite according to Rockefeller's conversations with Russo, is the Israel-Palestine conflict, with serious thinking at one stage revolving around the bizarre notion of giving Israeli citizens one million dollars each and relocating them all in the state of Arizona.


Money, Banking and the Federal Reserve

Thomas Jefferson and Andrew Jackson understood "The Monster". But to most Americans today, Federal Reserve is just a name on the dollar bill. They have no idea of what the central bank does to the economy, or to their own economic lives; of how and why it was founded and operates; or of the sound money and banking that could end the statism, inflation, and business cycles that the Fed generates.

31 Questions and Answers about the Internal Revenue Service
Revision 3.3
certified by


Paul Andrew Mitchell, B.A., M.S.

Citizen of California, Federal Witness,

Private Attorney General, Author and

Webmaster of the Supreme Law Library


Internet URL of home page:

http://www.supremelaw.org


Internet URL of this file:

http://www.supremelaw.org/sls/31answers.htm


Common Law Copyright

All Rights Reserved without Prejudice

Is the Internal Revenue Service (“IRS”) an organization within the U.S. Department of the Treasury?

1.Answer: No. The IRS is not an organization within the United States Department of the Treasury. The U.S. Department of the Treasury was organized by statutes now codified in Title 31 of the United States Code, abbreviated “31 U.S.C.” The only mention of the IRS anywhere in 31 U.S.C. §§ 301‑310 is an authorization for the President to appoint an Assistant General Counsel in the U.S. Department of the Treasury to be the Chief Counsel for the IRS. See 31 U.S.C. 301(f)(2).

At footnote 23 in the case of Chrysler Corp. v. Brown, 441 U.S. 281 (1979), the U.S. Supreme Court admitted that no organic Act for the IRS could be found, after they searched for such an Act all the way back to the Civil War, which ended in the year 1865 A.D. The Guarantee Clause in the U.S. Constitution guarantees the Rule of Law to all Americans (we are to be governed by Law and not by arbitrary bureaucrats). See Article IV, Section 4. Since there was no organic Act creating it, IRS is not a lawful organization.

2. If not an organization within the U.S. Department of the Treasury, then what exactly is the IRS?

Answer: The IRS appears to be a collection agency working for foreign banks and operating out of Puerto Rico under color of the Federal Alcohol Administration (“FAA”). But the FAA was promptly declared unconstitutional inside the 50 States by the U.S. Supreme Court in the case of U.S. v. Constantine, 296 U.S. 287 (1935), because Prohibition had already been repealed.


In 1998, the United States Court of Appeals for the First Circuit identified a second “Secretary of the Treasury” as a man by the name of Manual Díaz-Saldaña. See the definitions of “Secretary” and “Secretary or his delegate” at 27 CFR 26.11 (formerly 27 CFR 250.11), and the published decision in Used Tire International, Inc. v. Manual Díaz-Saldaña, court docket number 97‑2348, September 11, 1998. Both definitions mention Puerto Rico.

When all the evidence is examined objectively, IRS appears to be a money laundry, extortion racket, and conspiracy to engage in a pattern of racketeering activity, in violation of 18 U.S.C. 1951 and 1961 et seq. (“RICO”). Think of Puerto RICO (Racketeer Influenced and Corrupt Organizations Act); in other words, it is an organized crime syndicate operating under false and fraudulent pretenses. See also the Sherman Act and the Lanham Act.

3. By what legal authority, if any, has the IRS established offices inside the 50 States of the Union?

Answer: After much diligent research, several investigators have concluded that there is no known Act of Congress, nor any Executive Order, giving IRS lawful jurisdiction to operate within any of the 50 States of the Union.

Their presence within the 50 States appears to stem from certain Agreements on Coordination of Tax Administration (“ACTA”), which officials in those States have consummated with the Commissioner of Internal Revenue. A template for ACTA agreements can be found at the IRS Internet website and in the Supreme Law Library on the Internet.

However, those ACTA agreements are demonstrably fraudulent, for example, by expressly defining “IRS” as a lawful bureau within the U.S. Department of the Treasury. (See Answer to Question 1 above.) Moreover, those ACTA agreements also appear to violate State laws requiring competitive bidding before such a service contract can be awarded by a State government to any subcontractor. There is no evidence to indicate that ACTA agreements were reached after competitive bidding processes; on the contrary, the IRS is adamant about maintaining a monopoly syndicate.

4. Can IRS legally show “Department of the Treasury” on their outgoing mail?

Answer: No. It is obvious that such deceptive nomenclature is intended to convey the false impression that IRS is a lawful bureau or department within the U.S. Department of the Treasury. Federal laws prohibit the use of United States Mail for fraudulent purposes. Every piece of U.S. Mail sent from IRS with “Department of the Treasury” in the return address, is one count of mail fraud. See also 31 U.S.C. 333.


5. Does the U.S. Department of Justice have power of attorney to represent the IRS in federal court?

Answer: No. Although the U.S. Department of Justice (“DOJ”) does have power of attorney to represent federal agencies before federal courts, the IRS is not an “agency” as that term is legally defined in the Freedom of Information Act or in the Administrative Procedures Act. The governments of all federal Territories are expressly excluded from the definition of federal “agency” by Act of Congress. See 5 U.S.C. 551(1)(C).

Since IRS is domiciled in Puerto Rico (RICO?), it is thereby excluded from the definition of federal agencies which can be represented by the DOJ. The IRS Chief Counsel, appointed by the President under authority of 31 U.S.C. 301(f)(2), can appear, or appoint a delegate to appear in federal court on behalf of IRS and IRS employees. Again, see the Answer to Question 1 above. As far as powers of attorney are concerned, the chain of command begins with Congress, flows to the President, and then to the IRS Chief Counsel, and NOT to the U.S. Department of Justice.

6. Were the so-called 14th and 16th amendments properly ratified?

Answer: No. Neither was properly ratified. In the case of People v. Boxer (December 1992), docket number #S-030016, U.S. Senator Barbara Boxer fell totally silent in the face of an Application to the California Supreme Court by the People of California, for an ORDER compelling Senator Boxer to witness the material evidence against the so-called 16th amendment.

That so‑called “amendment” allegedly authorized federal income taxation, even though it contains no provision expressly repealing two Constitutional Clauses mandating that direct taxes must be apportioned. The Ninth Circuit Court of Appeals and the U.S. Supreme Court have both ruled that repeals by implication are not favored. See Crawford Fitting Co. et al. v. J.T. Gibbons, Inc., 482 U.S. 437, 442 (1987).

The material evidence in question was summarized in AFFIDAVIT’s that were properly executed and filed in that case. Boxer fell totally silent, thus rendering those affidavits the “truth of the case.” The so‑called 16th amendment has now been correctly identified as a major fraud upon the American People and the United States. Major fraud against the United States is a serious federal offense. See 18 U.S.C. 1031.

Similarly, the so-called 14th amendment was never properly ratified either. In the case of Dyett v. Turner, 439 P.2d 266, 270 (1968), the Utah Supreme Court recited numerous historical facts proving, beyond any shadow of a doubt, that the so‑called 14th amendment was likewise a major fraud upon the American People.


Those facts, in many cases, were Acts of the several State Legislatures voting for or against that proposal to amend the U.S. Constitution. The Supreme Law Library has a collection of references detailing this major fraud.

The U.S. Constitution requires that constitutional amendments be ratified by three-fourths of the several States. As such, their Acts are governed by the Full Faith and Credit Clause in the U.S. Constitution. See Article IV, Section 1.

Judging by the sheer amount of litigation its various sections have generated, particularly Section 1, the so‑called 14th amendment is one of the worst pieces of legislation ever written in American history. The phrase “subject to the jurisdiction of the United States” is properly understood to mean “subject to the municipal jurisdiction of Congress.” (See Answer to Question 19 below.)

For this one reason alone, the Congressional Resolution proposing the so-called 14th amendment is provably vague and therefore unconstitutional. See 14 Stat. 358-359, Joint Resolution No. 48, June 16, 1866.

7. Where are the statutes that create a specific liability for federal income taxes?

Answer: Section 1 of the Internal Revenue Code (“IRC”) contains no provisions creating a specific liability for taxes imposed by subtitle A. Aside from the statutes which apply only to federal government employees, pursuant to the Public Salary Tax Act, the only other statutes that create a specific liability for federal income taxes are those itemized in the definition of “Withholding agent” at IRC section 7701(a)(16). For example, see IRC section 1461. A separate liability statute for “employment” taxes imposed by subtitle C is found at IRC section 3403.

After a worker authorizes a payroll officer to withhold taxes, typically by completing Form W‑4, the payroll officer then becomes a withholding agent who is legally and specifically liable for payment of all taxes withheld from that worker’s paycheck. Until such time as those taxes are paid in full into the Treasury of the United States, the withholding agent is the only party who is legally liable for those taxes, not the worker. See IRC section 7809 (“Treasury of the United States”).

If the worker opts instead to complete a Withholding Exemption Certificate, consistent with IRC section 3402(n), the payroll officer is not thereby authorized to withhold any federal income taxes. In this latter situation, there is absolutely no liability for the worker or for the payroll officer; in other words, there is no liability PERIOD, specifically because there is no withholding agent.


8. Can a federal regulation create a specific liability, when no specific liability is created by the corresponding statute?

Answer: No. The U.S. Constitution vests all legislative power in the Congress of the United States. See Article I, Section 1. The Executive Branch of the federal government has no legislative power whatsoever. This means that agencies of the Executive Branch, and also the federal Courts in the Judicial Branch, are prohibited from making law.

If an Act of Congress fails to create a specific liability for any tax imposed by that Act, then there is no liability for that tax. Executive agencies have no authority to cure any such omission by using regulations to create a liability.

[A]n administrative agency may not create a criminal offense or any liability not sanctioned by the lawmaking authority, especially a liability for a tax or inspection fee.” See Commissioner of Internal Revenue v. Acker, 361 U.S. 87, 4 L.Ed.2d 127, 80 S.Ct. 144 (1959), and Independent Petroleum Corp. v. Fly, 141 F.2d 189 (5th Cir. 1944) as cited at 2 Am Jur 2d, p. 129, footnote 2 (1962 edition) [bold emphasis added]. However, this cite from American Jurisprudence has been removed from the 1994 edition of that legal encyclopedia.

9. The federal regulations create an income tax liability for what specific classes of people?

Answer: The regulations at 26 CFR 1.1-1 attempted to create a specific liability for all “citizens of the United States” and all “residents of the United States”. However, those regulations correspond to IRC section 1, which does not create a specific liability for taxes imposed by subtitle A.

Therefore, these regulations are an overly broad extension of the underlying statutory authority; as such, they are unconstitutional, null and void ab initio (from the beginning, in Latin). The Acker case cited above held that federal regulations can not exceed the underlying statutory authority. (See Answer to Question 8 above.)

10. How many classes of citizens are there, and how did this number come to be?

Answer: There are two (2) classes of citizens: State Citizens and federal citizens. The first class originates in the Qualifications Clauses in the U.S. Constitution, where the term “Citizen of the United States” is used. (See 1:2:2, 1:3:3 and 2:1:5.) Notice the UPPER-CASE “C” in “Citizen”.

The pertinent court cases have defined the term “United States” in these Clauses to mean “States United”, and the full term means “Citizen of ONE OF the States United”. See People v. De La Guerra, 40 Cal. 311, 337 (1870); Judge Pablo De La Guerra signed the California Constitution of 1849, when California first joined the Union. Similar terms are found in the Diversity Clause at Article III, Section 2, Clause 1, and in the Privileges and Immunities Clause at Article IV, Section 2, Clause 1. Prior to the Civil War, there was only one (1) class of Citizens under American Law. See the holding in Pannill v. Roanoke, 252 F. 910, 914‑915 (1918), for definitive authority on this key point.

The second class originates in the 1866 Civil Rights Act, where the term “citizen of the United States” is used. This Act was later codified at 42 U.S.C. 1983. Notice the lower-case “c” in “citizen”. The pertinent court cases have held that Congress thereby created a municipal franchise primarily for members of the Negro race, who were freed by President Lincoln’s Emancipation Proclamation (a war measure), and later by the Thirteenth Amendment banning slavery and involuntary servitude. Compelling payment of a “tax” for which there is no liability statute is tantamount to involuntary servitude, and extortion.

Instead of using the unique term “federal citizen”, as found in Black’s Law Dictionary, Sixth Edition, it is now clear that the Radical Republicans who sponsored the 1866 Civil Rights Act were attempting to confuse these two classes of citizens. Then, they attempted to elevate this second class to constitutional status, by proposing a 14th amendment to the U.S. Constitution. As we now know, that proposal was never ratified. (See Answer to Question 6 above.)

Numerous court cases have struggled to clarify the important differences between the two classes. One of the most definitive, and dispositive cases, is Pannill v. Roanoke, 252 F. 910, 914‑915 (1918), which clearly held that federal citizens had no standing to sue under the Diversity Clause, because they were not even contemplated when Article III in the U.S. Constitution was first being drafted, circa 1787 A.D.

Another is Ex parte Knowles, 5 Cal. 300 (1855) in which the California Supreme Court ruled that there was no such thing as a “citizen of the United States” (as of the year 1855 A.D.). Only federal citizens have standing to invoke 42 U.S.C. 1983; whereas State Citizens do not. See Wadleigh v. Newhall, 136 F. 941 (C.C. Cal. 1905).

Many more cases can be cited to confirm the existence of two classes of citizens under American Law. These cases are thoroughly documented in the book entitled “The Federal Zone: Cracking the Code of Internal Revenue” by Paul Andrew Mitchell, B.A., M.S., now in its eleventh edition. See also the pleadings in the case of USA v. Gilbertson, also in the Supreme Law Library.


11. Can one be a State Citizen, without also being a federal citizen?

Answer: Yes. The 1866 Civil Rights Act was municipal law, confined to the District of Columbia and other limited areas where Congress is the “state” government with exclusive legislative jurisdiction there. These areas are now identified as “the federal zone.” (Think of it as the blue field on the American flag; the stars on the flag are the 50 States.) As such, the 1866 Civil Rights Act had no effect whatsoever upon the lawful status of State Citizens, then or now.

Several courts have already recognized our Right to be State Citizens without also becoming federal citizens. For excellent examples, see State v. Fowler, 41 La. Ann. 380, 6 S. 602 (1889) and Gardina v. Board of Registrars, 160 Ala. 155, 48 S. 788, 791 (1909). The Maine Supreme Court also clarified the issue by explaining our “Right of Election” or “freedom of choice,” namely, our freedom to choose between two different forms of government. See 44 Maine 518 (1859), Hathaway, J. dissenting.

Since the Guarantee Clause does not require the federal government to guarantee a Republican Form of Government to the federal zone, Congress is free to create a different form of government there, and so it has. In his dissenting opinion in Downes v. Bidwell, 182 U.S. 244 at 380 (1901), Supreme Court Justice Harlan called it an absolute legislative democracy.

But, State Citizens are under no legal obligation to join or pledge any allegiance to that legislative democracy; their allegiance is to one or more of the several States of the Union (i.e. the white stars on the American flag, not the blue field).

12. Who was Frank Brushaber, and why was his U.S. Supreme Court case so important?

Answer: Frank Brushaber was the Plaintiff in the case of Brushaber v. Union Pacific Railroad Company, 240 U.S. 1 (1916), the first U.S. Supreme Court case to consider the so‑called 16th amendment. Brushaber identified himself as a Citizen of New York State and a resident of the Borough of Brooklyn, in the city of New York, and nobody challenged that claim.

The Union Pacific Railroad Company was a federal corporation created by Act of Congress to build a railroad through Utah (from the Union to the Pacific), at a time when Utah was a federal Territory, i.e. inside the federal zone.

Brushaber’s attorney committed an error by arguing that the company had been chartered by the State of Utah, but Utah was not a State of the Union when Congress first created that corporation.


Brushaber had purchased stock issued by the company. He then sued the company to recover taxes that Congress had imposed upon the dividends paid to its stockholders. The U.S. Supreme Court ruled against Frank Brushaber, and upheld the tax as a lawful excise, or indirect tax.

The most interesting result of the Court’s ruling was a Treasury Decision (“T.D.”) that the U.S. Department of the Treasury later issued as a direct consequence of the high Court’s opinion. In T.D. 2313, the U.S. Treasury Department expressly cited the Brushaber decision, and it identified Frank Brushaber as a “nonresident alien” and the Union Pacific Railroad Company as a “domestic corporation”. This Treasury Decision has never been modified or repealed.

T.D. 2313 is crucial evidence proving that the income tax provisions of the IRC are municipal law, with no territorial jurisdiction inside the 50 States of the Union. The U.S. Secretary of the Treasury who approved T.D. 2313 had no authority to extend the holding in the Brushaber case to anyone or anything not a proper Party to that court action.

Thus, there is no escaping the conclusion that Frank Brushaber was the nonresident alien to which that Treasury Decision refers. Accordingly, all State Citizens are nonresident aliens with respect to the municipal jurisdiction of Congress, i.e. the federal zone.

13. What is a “Withholding agent”?

Answer: (See Answer to Question 7 first.) The term “Withholding agent” is legally defined at IRC section 7701(a)(16). It is further defined by the statutes itemized in that section, e.g. IRC 1461 where liability for funds withheld is clearly assigned. In plain English, a “withholding agent” is a person who is responsible for withholding taxes from a worker’s paycheck, and then paying those taxes into the Treasury of the United States, typically on a quarterly basis. See IRC section 7809.

One cannot become a withholding agent unless workers first authorize taxes to be withheld from their paychecks. This authorization is typically done when workers opt to execute a valid W‑4 “Employee’s Withholding Allowance Certificate.” In plain English, by signing a W‑4 workers designate themselves as “employees” and certify they are allowing withholding to occur.

If workers do not execute a valid W‑4 form, a company’s payroll officer is not authorized to withhold any federal income taxes from their paychecks. In other words, the payroll officer does not have “permission” or “power of attorney” to withhold taxes, until and unless workers authorize or “allow” that withholding ‑‑ by signing Form W‑4 knowingly, intentionally and voluntarily.


Pay particular attention to the term “Employee” in the title of this form. A properly executed Form W‑4 creates the presumption that the workers wish to be treated as if they were “employees” of the federal government. Obviously, for people who do not work for the federal government, such a presumption is a legal fiction, at best.

14. What is a “Withholding Exemption Certificate”?

Answer: A “Withholding Exemption Certificate” is an alternative to Form W‑4, authorized by IRC section 3402(n) and executed in lieu of Form W‑4. Although section 3402(n) does authorize this Certificate, the IRS has never added a corresponding form to its forms catalog (see the IRS “Printed Products Catalog”).

In the absence of an official IRS form, workers can use the language of section 3402(n) to create their own Certificates. In simple language, the worker certifies that s/he had no federal income tax liability last year, and anticipates no federal income tax liability during the current calendar year. Because there are no liability statutes for workers in the private sector, this certification is easy to justify.

Many public and private institutions have created their own form for the Withholding Exemption Certificate, e.g. California Franchise Tax Board, and Johns Hopkins University in Baltimore, Maryland. This fact can be confirmed by using any search engine, e.g. google.com, to locate occurrences of the term “withholding exemption certificate” on the Internet. This term occurs several times in IRC section 3402.

15. What is “tax evasion” and who might be guilty of this crime?

Answer: Tax evasion” is the crime of evading a lawful tax. In the context of federal income taxes, this crime can only be committed by persons who have a legal liability to pay, i.e. the withholding agent. If one is not employed by the federal government, one is not subject to the Public Salary Tax Act unless one chooses to be treated “as if” one is a federal government “employee.” This is typically done by executing a valid Form W‑4.

However, as discussed above, Form W‑4 is not mandatory for workers who are not “employed” by the federal government. Corporations chartered by the 50 States of the Union are technically “foreign” corporations with respect to the IRC; they are decidedly not the federal government, and should not be regarded “as if” they are the federal government, particularly when they were never created by any Act of Congress.


Moreover, the Indiana Supreme Court has ruled that Congress can only create a corporation in its capacity as the Legislature for the federal zone. Such corporations are the only “domestic” corporations under the pertinent federal laws. This writer’s essay entitled “A Cogent Summary of Federal Jurisdictions” clarifies this important distinction between “foreign” and “domestic” corporations in simple, straightforward language.

If Congress were authorized to create national corporations, such a questionable authority would invade States’ rights reserved to them by the Tenth Amendment, namely, the right to charter their own domestic corporations. The repeal of Prohibition left the Tenth Amendment unqualified. See the Constantine case supra.

For purposes of the IRC, the term “employer” refers only to federal government agencies, and an “employee” is a person who works for such an “employer”.

16. Why does IRS Form 1040 not require a Notary Public to notarize a taxpayer’s signature?

Answer: This question is one of the fastest ways to unravel the fraudulent nature of federal income taxes. At 28 U.S.C. section 1746, Congress authorized written verifications to be executed under penalty of perjury without the need for a Notary Public, i.e. to witness one’s signature.

This statute identifies two different formats for such written verifications: (1) those executed outside the “United States” and (2) those executed inside the “United States”. These two formats correspond to sections 1746(1) and 1746(2), respectively.

What is extremely revealing in this statute is the format for verifications executed “outside the United States”. In this latter format, the statute adds the qualifying phrase “under the laws of the United States of America”.

Clearly, the terms “United States” and “United States of America” are both used in this same statute. They are not one and the same. The former refers to the federal government -- in the U.S. Constitution and throughout most federal statutes. The latter refers to the 50 States that are united by, and under, the U.S. Constitution. 28 U.S.C. 1746 is the only federal statute in all of Title 28 of the United States Code that utilizes the term “United States of America”, as such.

It is painfully if not immediately obvious, then, that verifications made under penalty of perjury are outside the 50 States of the Union (read “the State zone”) if and when they are executed inside the “United States” (read “the federal zone”).


Likewise, verifications made under penalty of perjury are inside the 50 States of the Union, if and when they are executed outside the “United States”.

The format for signatures on Form 1040 is the one for verifications made inside the United States (federal zone) and outside the United States of America (State zone).

17. Does the term “United States” have multiple legal meanings and, if so, what are they?

Answer: Yes. The term has several meanings. The term "United States" may be used in any one of several senses. [1] It may be merely the name of a sovereign occupying the position analogous to that of other sovereigns in the family of nations. [2] It may designate the territory over which the sovereignty of the United States extends, or [3] it may be the collective name of the States which are united by and under the Constitution. See Hooven & Allison Co. v. Evatt, 324 U.S. 652 (1945) [bold emphasis, brackets and numbers added for clarity].

This is the very same definition that is found in Black’s Law Dictionary, Sixth Edition. The second of these three meanings refers to the federal zone and to Congress only when it is legislating in its municipal capacity. For example, Congress is legislating in its municipal capacity whenever it creates a federal corporation, like the United States Postal Service.

It is terribly revealing of the manifold frauds discussed in these Answers, that the definition of “United States” has now been removed from the Seventh Edition of Black’s Law Dictionary.

18. Is the term “income” defined in the IRC and, if not, where is it defined?

Answer: The Eighth Circuit Court of Appeals has already ruled that the term “income” is not defined anywhere in the IRC: “The general term ‘income’ is not defined in the Internal Revenue Code.” U.S. v. Ballard, 535 F.2d 400, 404 (8th Circuit, 1976).

Moreover, in Mark Eisner v. Myrtle H. Macomber, 252 U.S. 189 (1920), the high Court told Congress it could not legislate any definition of “income” because that term was believed to be in the U.S. Constitution. The Eisner case was predicated on the ratification of the 16th amendment, which would have introduced the term “income” into the U.S. Constitution for the very first time (but only if that amendment had been properly ratified).

In Merchant's Loan & Trust Co. v. Smietanka, 255 U.S. 509 (1921), the high Court defined “income” to mean the profit or gain derived from corporate activities. In that instance, the tax is a lawful excise tax imposed upon the corporate privilege of limited liability, i.e. the liabilities of a corporation do not reach its officers, employees, directors or stockholders.

19. What is municipal law, and are the IRC’s income tax provisions municipal law, or not?

Answer: Yes. The IRC’s income tax provisions are municipal law. Municipal law is law that is enacted to govern the internal affairs of a sovereign State; in legal circles, it is also known as Private International Law. Under American Law, it has a much wider meaning than the ordinances enacted by the governing body of a municipality, i.e. city council or county board of supervisors. In fact, American legal encyclopedias define “municipal” to mean “internal”, and for this reason alone, the Internal Revenue Code is really a Municipal Revenue Code.

A mountain of additional evidence has now been assembled and published in the book “The Federal Zone” to prove that the IRC’s income tax provisions are municipal law.

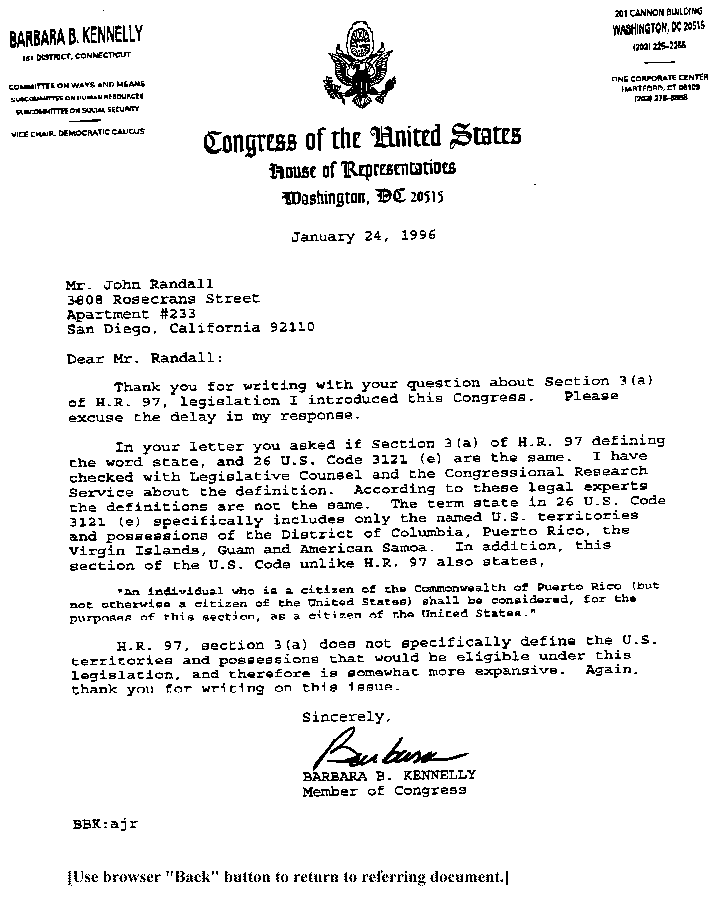
One of the most famous pieces of evidence is a letter from a Connecticut Congresswoman, summarizing the advice of legal experts employed by the Congressional Research Service and the Legislative Counsel. Their advice confirmed that the meaning of “State” at IRC section 3121(e) is restricted to the named territories and possessions of D.C., Guam, Virgin Islands, American Samoa, and Puerto Rico.

In other words, the term “State” in that statute, and in all similar federal statutes, includes ONLY the places expressly named, and no more.

20. What does it mean if my State is not mentioned in any of the federal income tax statutes?

The general rule is that federal government powers must be expressed and enumerated. For example, the U.S. Constitution is a grant of enumerated powers. If a power is not enumerated in the U.S. Constitution, then Congress does not have any authority to exercise that power. This rule is tersely expressed in the Ninth Amendment, in the Bill of Rights.

If California is not mentioned in any of the federal income tax statutes, then those statutes have no force or effect within that State. This is also true of all 50 States.

Strictly speaking, the omission or exclusion of anyone or any thing from a federal statute can be used to infer that the omission or exclusion was intentional by Congress. In Latin, this is tersely stated as follows: Inclusio unius est exclusio alterius. In English, this phrase is literally translated: Inclusion of one thing is the exclusion of all other things [that are not mentioned]. This phrase can be found in any edition of Black’s Law Dictionary; it is a maxim of statutory construction.

The many different definitions of the term “State” that are found in federal laws are intentionally written to appear as if they include the 50 States PLUS the other places mentioned. As the legal experts in Congress have now confirmed, this is NOT the correct way to interpret, or to construct, these statutes.

If a place is not mentioned, every American may correctly infer that the omission of that place from a federal statute was an intentional act of Congress. Whenever it wants to do so, Congress knows how to define the term “United States” to mean the 50 States of the Union. See IRC section 4612(a)(4)(A).

21. In what other ways is the IRC deliberately vague, and what are the real implications for the average American?

There are numerous other ways in which the IRC is deliberately vague. The absence of any legal definition for the term “income” is a classic deception. The IRS enforces the Code as a tax on everything that “comes in,” but nothing could be further from the truth. “Income” is decidedly NOT everything that “comes in.”

More importantly, the fact that this vagueness is deliberate is sufficient grounds for concluding that the entire Code is null, void and unconstitutional, for violating our fundamental Right to know the nature and cause of any accusation, as guaranteed by the Sixth Amendment in the Bill of Rights.

Whether the vagueness is deliberate or not, any statute is unconstitutionally void if it is vague. If a statute is void for vagueness, the situation is the same as if it had never been enacted at all, and for this reason it can be ignored entirely.

22. Has Title 26 of the United States Code (“U.S.C.”) ever been enacted into positive law, and what are the legal implications if Title 26 has not been enacted into positive law?

Answer: No. Another, less obvious case of deliberate deception is the statute at IRC section 7851(a)(6)(A), where it states that the provisions of subtitle F shall take effect on the day after the date of enactment of “this title”. Because the term “this title” is not defined anywhere in the IRC, least of all in the section dedicated to definitions, one is forced to look elsewhere for its meaning, or to derive its meaning from context.

Throughout Title 28 of the United States Code -- the laws which govern all the federal courts -- the term “this title” clearly refers to Title 28. This fact would tend to support a conclusion that “this title”, as that term is used in the IRC, refers to Title 26 of the United States Code. However, Title 26 has never been enacted into positive law, as such.

Even though all federal judges may know the secret meaning of “this title”, they are men and women of UNcommon intelligence. The U.S. Supreme Court’s test for vagueness is violated whenever men and women of common intelligence must necessarily guess at the meaning and differ as to the application of a vague statute. See Connally et al. v. General Construction Co., 269 U.S. 385, 391 (1926). Thus, federal judges are applying the wrong test for vagueness.

Accordingly, the provisions of subtitle F have never taken effect. (“F” is for enForcement!) This subtitle contains all of the enforcement statutes of the IRC, e.g. filing requirements, penalties for failure to file and tax evasion, grants of court jurisdiction over liens, levies and seizures, summons enforcement and so on.

In other words, the IRC is a big pile of Code without any teeth; as such, it can impose no legal obligations upon anyone, not even people with dentures!

23. What federal courts are authorized to prosecute income tax crimes?

This question must be addressed in view of the Answer to Question 22 above. Although it may appear that certain statutes in the IRC grant original jurisdiction to federal district courts, to institute prosecutions of income tax crimes, none of the statutes found in subtitle F has ever taken effect. For this reason, those statutes do not authorize the federal courts to do anything at all. As always, appearances can be very deceiving. Remember the Wizard of Oz or the mad tea party of Alice in Wonderland?

On the other hand, the federal criminal Code at Title 18, U.S.C., does grant general authority to the District Courts of the United States (“DCUS”) to prosecute violations of the statutes found in that Code. See 18 U.S.C. 3231.

It is very important to appreciate the fact that these courts are not the same as the United States District Courts (“USDC”). The DCUS are constitutional courts that originate in Article III of the U.S. Constitution. The USDC are territorial tribunals, or legislative courts, that originate in Article IV, Section 3, Clause 2 of the U.S. Constitution, also known as the Territory Clause.

This author’s OPENING BRIEF to the Eighth Circuit on behalf of the Defendant in USA v. Gilbertson cites numerous court cases that have already clarified the all important distinction between these two classes of federal district courts. For example, in Balzac v. Porto Rico, 258 U.S. 298 at 312 (1922), the high Court held that the USDC belongs in the federal Territories. This author’s OPENING BRIEF to the Ninth Circuit in Mitchell v. AOL Time Warner, Inc. et al. develops this theme in even greater detail; begin reading at section “7(e)”.

The USDC, as such, appear to lack any lawful authorities to prosecute income tax crimes. The USDC are legislative tribunals where summary proceedings dominate.

For example, under the federal statute at 28 U.S.C. 1292, the U.S. Courts of Appeal have no appellate jurisdiction to review interlocutory orders issued by the USDC. Further details on this point are available in the Press Release entitled “Private Attorney General Cracks Title 28 of the United States Code” and dated November 26, 2001 A.D.

24. Are federal judges required to pay income taxes on their pay, and what are the real implications if they do pay taxes on their pay?

Answer: No. Federal judges who are appointed to preside on the District Courts of the United States –- the Article III constitutional courts –- are immune from any taxation of their pay, by constitutional mandate.

The fact that all federal judges are currently paying taxes on their pay is proof of undue influence by the IRS, posing as a duly authorized agency of the Executive Branch. See Evans v. Gore, 253 U.S. 245 (1920).

Even if the IRS were a lawful bureau or department within the U.S. Department of the Treasury (which they are NOT), the existence of undue influence by the Executive Branch would violate the fundamental principle of Separation of Powers. This principle, in theory, keeps the 3 branches of the federal government confined to their respective areas, and prevents any one branch from usurping the lawful powers that rightly belong to the other two branches.

The Separation of Powers principle is succinctly defined in Williams v. United States, 289 U.S. 553 (1933); however, in that decision the Supreme Court erred by defining “Party” to mean only Plaintiffs in Article III, contrary to the definition of “Party” that is found in Bouvier’s Law Dictionary (1856).

The federal judiciary, contemplated by the organic U.S. Constitution, was intended to be independent and unbiased. These two qualities are the essence, or sine qua non of judicial power, i.e. without which there is nothing. Undue influence obviously violates these two qualities. See Evans v. Gore supra.

In Lord v. Kelley, 240 F.Supp. 167, 169 (1965), the federal judge in that case was honest enough to admit, in his published opinion, that federal judges routinely rule in favor of the IRS, because they fear the retaliation that might result from ruling against the IRS. There you have it, from the horse’s mouth!

In front of a class of law students at the University of Arizona in January of 1997, Chief Justice William H. Rehnquist openly admitted that all federal judges are currently paying taxes on their judicial pay. This writer was an eyewitness to that statement by the Chief Justice of the U.S. Supreme Court -– the highest Court in the land.

Thus, all federal judges are now material witnesses to the practice of concealing the Withholding Exemption Certificate from them, when they were first hired as “employees” of the federal judiciary. As material witnesses, they are thereby disqualified from presiding on all federal income tax cases.

25. Can federal grand juries issue valid indictments against illegal tax protesters?

Answer: No. Federal grand juries cannot issue valid indictments against illegal tax protesters. Protest has never been illegal in America, because the First Amendment guarantees our fundamental Right to express our objections to any government actions, in written and in spoken words.

Strictly speaking, the term “illegal” cannot modify the noun “protesters” because to do so would constitute a violation of the First Amendment in the Bill of Rights, one of the most magnificent constitutional provisions ever written.

Accordingly, for the term “illegal tax protester” to survive this obvious constitutional challenge, the term “illegal” must modify the noun “tax”. An illegal tax protester is, therefore, someone who is protesting an illegal tax. Such an act of protest is protected by the First Amendment, and cannot be a crime.

Protest is also recognized and honored by the Uniform Commercial Code; the phrases “under protest” and “without prejudice” are sufficient to reserve all of one’s fundamental Rights at law. See U.C.C. 1-207 (UCCA 1207 in California).

By the way, the federal U.C.C. is also municipal law. See the Answer to Question 19 above, and 77 Stat. 630, P.L. 88‑243, December 30, 1963 (one month after President John F. Kennedy was murdered).

26. Do IRS agents ever tamper with federal grand juries, and how is this routinely done?

Answer: Yes. IRS agents routinely tamper with federal grand juries, most often by misrepresenting themselves, under oath, as lawful employees and “Special Agents” of the federal government, and by misrepresenting the provisions of subtitle F as having any legal force or effect. Such false representations of fact violate Section 43(a) of the Lanham Act, uncodified at 15 U.S.C. 1125(a). (Title 15 of the United States Code has not been enacted into positive law either.)

They tamper with grand juries by acting as if “income” is everything that “comes in”, when there is no such definition anywhere in the IRC. Such false descriptions of fact also violate Section 43(a) of the Lanham Act.

They tamper with grand juries by presenting documentary evidence which they had no authority to acquire, in the first instance, such as bank records. Bank signature cards do not constitute competent waivers of their customers’ fundamental Rights to privacy, as secured by the Fourth Amendment. The high standard for waivers of fundamental Rights was established by the U.S. Supreme Court in Brady v. U.S., 397 U.S. 742, 748 (1970).

IRS agents tamper with grand juries by creating and maintaining the false and fraudulent pretenses that the IRC is not vague, or that the income tax provisions have any legal force or effect inside the 50 States of the Union, when those provisions do not.

These are all forms of perjury, as well, and possibly also misprision of perjury by omission, i.e. serious federal offenses.

Finally, there is ample evidence that IRS agents bribe U.S. Attorneys, federal judges, and even the Office of the President with huge kickbacks, every time a criminal indictment is issued by a federal grand jury against an illegal tax protester. (See the Answer to Question 25 above.) These kick‑backs range from $25,000 to $35,000 in CASH! They also violate the Anti-Kickback Act of 1986, which penalizes the payment of kickbacks from federal government subcontractors. See 41 U.S.C. 51 et seq.

As a trust domiciled in Puerto Rico, the IRS is, without a doubt, a federal government subcontractor that is subject to this Act. See 31 U.S.C. 1321(a)(62). The systematic and premeditated pattern of racketeering by IRS employees also establishes probable cause to dismantle the IRS permanently for violating the Sherman Antitrust Act, first enacted in the year 1890 A.D. See 26 Stat. 209 (1890) (uncodified at 15 U.S.C. 1 et seq.)

27. What is “The Kickback Racket,” and where can I find evidence of its existence?

The evidence of this “kickback racket” was first discovered in a table of delegation orders, on a page within the Internal Revenue Manual (“IRM”) -- the internal policy and procedure manual for all IRS employees.


Subsequently, this writer submitted a lawful request, under the Freedom of Information Act, for a certified list of all payments that had ever been made under color of these delegation orders in the IRM. Mr. Mark L. Zolton, a tax law specialist within the Internal Revenue Service, responded on IRS letterhead, transmitted via U.S. Mail, that few records existed for these “awards” because most of them were paid in cash!

When this evidence was properly presented to a federal judge, who had been asked to enforce a federal grand jury subpoena against a small business in Arizona, he ended up obstructing all 28 pieces of U.S. Mail we had transmitted to that grand jury.

Obstruction of correspondence is a serious federal offense, and federal judges have no authority whatsoever to intercept U.S. Mail. See 18 U.S.C. 1702.

Obviously, the federal judge -- John M. Roll -- did NOT want the grand jury in that case to know anything about these kickbacks. They found out anyway, because of the manner in which this writer defended that small business, as its Vice President for Legal Affairs.

28. Can the IRS levy bank accounts without a valid court order?

Answer: No. The Fifth Amendment prohibits all deprivations of life, liberty, or property without due process of law. Due Process of Law is another honored and well developed feature of American constitutional practice. Put simply, it requires Notice and Hearing before any property can be seized by any federal government employees, agents, departments or agencies.

A levy against a bank account is a forced seizure of property, i.e. the funds on deposit in that account. No such seizure can occur unless due process of law has first run its course. This means notice, hearing, and deliberate adjudication of all the pertinent issues of law and fact.

Only after this process has run its proper or “due” course, can a valid court order be issued. The holding in U.S. v. O’Dell, 160 F.2d 304 (6th Cir. 1947), makes it very clear that the IRS can only levy a bank account after first obtaining a Warrant of Distraint, or court ORDER. And, of course, no court ORDER could ever be obtained unless all affected Parties had first enjoyed their “day in court.”

29. Do federal income tax revenues pay for any government services and, if so, which government services are funded by federal income taxes?

Answer: No. The money trail is very difficult to follow, in this instance, because the IRS is technically a trust with a domicile in Puerto Rico. See 31 U.S.C. 1321(a)(62). As such, their records are protected by laws which guarantee the privacy of trust records within that territorial jurisdiction, provided that the trust is not also violating the Sherman Antitrust Act.

They are technically not an “agency” of the federal government, as that term is defined in the Freedom of Information Act and in the Administrative Procedures Act. The governments of the federal territories are expressly excluded from the definition of “agency” in those Acts of Congress. See 5 U.S.C. 551(1)(C). (See also the Answer to Question 5 above.)

All evidence indicates that they are a money laundry, extortion racket, and conspiracy to engage in a pattern of racketeering activity, in violation of 18 U.S.C. 1951 and 1961 et seq.

They appear to be laundering huge sums of money into foreign banks, mostly in Europe, and quite possibly into the Vatican. See the national policy on money laundering at 31 U.S.C. 5341.

The final report of the Grace Commission, convened under President Ronald Reagan, quietly admitted that none of the funds they collect from federal income taxes goes to pay for any federal government services. The Grace Commission found that those funds were being used to pay for interest on the federal debt, and income transfer payments to beneficiaries of entitlement programs like federal pension plans.

30. How can the Freedom of Information Act (“FOIA”) help me to answer other key tax questions?

The availability of correct information about federal government operations is fundamental to maintaining the freedom of the American People. The Freedom of Information Act (“FOIA”), at 5 U.S.C. 552 et seq., was intended to make government documents available with a minimal amount of effort by the People.

As long as a document is not protected by one of the reasonable exemptions itemized in the FOIA, a requester need only submit a brief letter to the agency having custody of the requested document(s). If the requested document is not produced within 20 working days (excluding weekends and federal holidays), the requester need only prepare a single appeal letter.

If the requested document is not produced within another 20 working days after the date of the appeal letter, the requester is automatically allowed to petition a District Court of the United States (Article III DCUS, not the Article IV USDC) -- to compel production of the requested document, and judicially to enjoin the improper withholding of same. See 5 U.S.C. 552(a)(4)(B). The general rule is that statutes conferring original jurisdiction on federal district courts must be strictly construed.


This writer has pioneered the application of the FOIA to request certified copies of statutes and regulations which should exist, but do not exist. A typical request anyone can make, to which the U.S. Treasury has now fallen totally silent, is for a certified copy of all statutes which create a specific liability for taxes imposed by subtitle A of the IRC. For example, see the FOIA request that this writer prepared for author Lynne Meredith.

Of course, by now we already know the answer to this question, before asking it. (Good lawyers always know the answers to their questions, before asking them.)

It should also be clear that such a FOIA request should not be directed to the IRS, because they are not an “agency” as that term is defined at 5 U.S.C. 551(1)(C). Address it instead to the Disclosure Officer, Disclosure Services, Room 1054-MT, U.S. Department of the Treasury, Washington 20220, DISTRICT OF COLUMBIA, USA. This is the format for “foreign” addresses, as explained in USPS Publication #221.

As James Madison once wrote, “A popular government without popular information or the means of acquiring it, is but a Prologue to a Farce or a Tragedy or perhaps both. Knowledge will forever govern ignorance, and a people who mean to be their own Governors, must arm themselves with the power knowledge gives."

31. Where can I find more information, and still protect my privacy?

There are many civic organizations throughout America who have dedicated their precious time and energy to acquire and disseminate widely these documented truths about the Internal Revenue Service and the Internal Revenue Code.

The Internet’s World Wide Web (“www”) is perhaps the best single source of information (and disinformation) about the IRS, and the major problems now confirmed in the IRC and in the mountains of related policies, procedures, practices, customs, rules, regulations, forms and schedules.

Learn to become a sophisticated consumer of information, and the knowledge you seek will be yours to keep and share -- with those you love and endeavor to free from this terrible plague that persists in America.